Tax On Betting Winnings
HM Revenue and Customs does not charge Income Tax or Capital Gains Tax on betting winnings collected by UK residents. The tax burden rests on the licensed operators taking the wagers, not on the individual backing a selection.
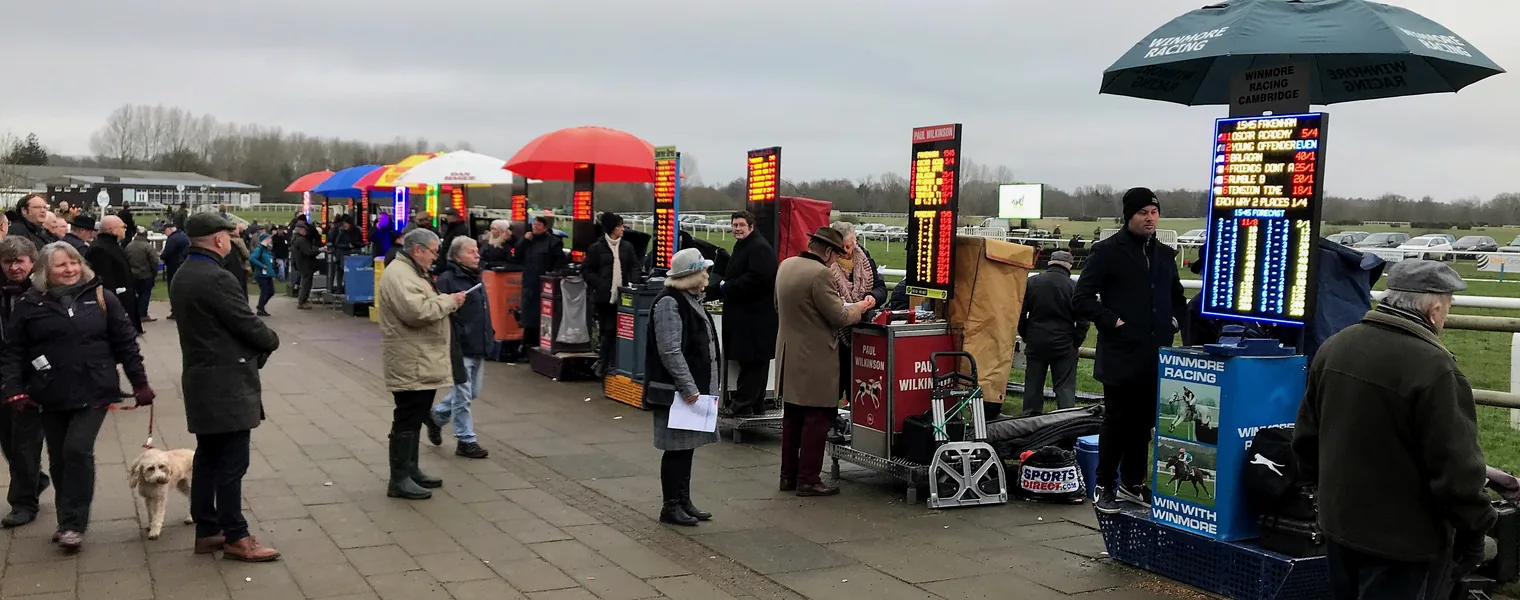
Secondary tax guidance suggests that money received from betting or gambling does not qualify as taxable income. Secondary sources suggest this tax-free treatment for punters dates back to 2001. Even when an individual wagers full-time, secondary sources indicate professional gamblers in the United Kingdom pay no gambling tax on their winnings.
The Personal Exemption and Operator Duty
Individual players do not declare betting payouts on a Self Assessment return. Instead, HMRC collects revenue via General Betting Duty, a direct charge on the companies providing the market.
Guidance issued by HMRC confirms that operators, not punters, are liable for General Betting Duty on bookmaker profits. Companies liable for the duty must register with HMRC and pay the sums owed on those profits directly to the Exchequer.
The basic retail structure has remained consistent. Under HMRC Excise Notice 451a, General Betting Duty is charged at 15% of a bookmaker’s profits from general bets or pool bets on horse racing or dog racing made by a customer inside a betting shop. For retail customers wagering over the counter, deductions from winnings can form part of how the bookmaker accounts for this duty.
Betting exchanges face their own distinct assessment. General Betting Duty applies to any fee or commission amount an exchange platform charges to any UK person who uses its facilities to place bets.
Shop Bets, Exchanges, and On-Course Exceptions
The tax regime treats physical racing venues differently from high-street shops or digital exchanges.
Betting Category Current Duty Rate Liability Holder
High-street betting shops 15% of profits Bookmaker
Betting exchange user charges 15% of charges Exchange operator
On-course pitch bookmakers 0% (exempt) Exempt from HMRC registration
Remote general bets (pre-April 2027) 15% of profits Remote operator
Pitch bookmakers working trackside avoid the duty entirely. HMRC guidance explicitly states that a bookmaker who only takes on-course bets does not need to pay General Betting Duty. Nor does that on-course operator need to notify HMRC about the bookmaking business.
The rule creates a strict operational divide between high-street retail operations, digital betting hubs, and physical trackside pitches.
The April 2027 Split for Remote Operators
The fiscal terms governing remote operators are scheduled to shift.The ten-percentage-point increase will not hit every digital wager. HMRC guidance outlines two specific exemptions that preserve the 15% rate:
- Remote betting conducted wholly on UK horse racing.
- Bets placed through self-service betting terminals located inside licensed betting premises.
Both categories remain ring-fenced at the standard 15% duty rate after April 2027. The Treasury designed the split to protect terrestrial shop infrastructure and domestic horse racing while extracting higher yields from broader online casino wagers, sportsbooks, and digital fixed-odds products.
The Boundary with Taxable Trading
The core tax position for the punter remains uncomplicated: if you place a bet and win, HMRC claims nothing from the payout.
The division becomes relevant only when gambling-adjacent activities cross into employment or commercial trade. Winnings derived from personal wagers carry zero personal tax liability. When activities shift into providing commercial services, running syndicates as an enterprise, or receiving compensation for industry-related work, the proceeds move into standard trading income rules.
For the bettor placing personal wagers with licensed bookmakers, exchanges, or racecourse rails, the cash received is entirely free of personal tax. The commercial bookmakers will absorb the upcoming 25% remote duty adjustment from April 2027.